I was watching Gov. Mike Leavitt on PBS field questions about health care reform. He did a fine job fielding questions and defending conservative values that bigger government is not the answer to our health care problems. Yes, our country is an unfinished pyramid, but the all-seeing eye at the top is God, not the government. That said, I think many miss the real reasons why health care costs are so high.
Financial Reform
The real problem with cost in America are financial and our system of borrowing and lending. It truly is a system of bondage. As I understand the banking system, banks can borrow tax money from the FED at prime which is nearly free and currently at 0% is free. Then they turn around and lend that money back to us for home loans at a higher interest rate of 5-6%. But what is not discussed is that in addition to the profit margin built into the higher interest rate, the banks also bind the borrower to an unfair amortization schedule that collects 95% interest for 20 years on a 30-year loan assuming minimum payments. On the other hand, when an American family saves money, they earn only 5% interest which doesn't accrue significant interest until after 20 year. This creates the classes in America. There are the working middle and lower classes which pay the interest and a fortunate few who have broken through the interest barrier and earn the interest and are free from paying it. This system also creates inflation as the only way to gain significant equity (if making minimum payments) is for the value of the house to go up.
Sub-Prime Loans
Banks would have us believe that sub-prime borrowers who defaulted on their loans are the cause for the housing bubble bursting. This is a terrible half-truth. What most people don't know is that the banking system operates on a system of fractional reserve lending. That means that for every 1$ they borrow from the FED or elsewhere, they can lend 10$ or more. That means that if a person defaults on their loan and the bank repos. and resells their house for 40c/1$, the bank still made 30c plus all the interest already paid. Also, people don't understand that rich people who were "upside down" defaulted on their second homes and vacation homes as much as the sub-prime lenders did. While this shouldn't have hurt the banks, this did hurt AIG who was the major underwriter for mortgage insurance on all those sub-prime loans that didn't collect an initial down payment. AIG couldn't or wouldn't pay the banks all the default mortgage claims.
Mortgage Backed Securities
If a borrower defaults on a loan, has their house repossessed and resold at 40c/1$, shouldn't that still result in a profit for the bank because of fractional reserve lending? If this is so, why did some banks fail? The reason some banks failed was because they were fooled into "leveraging" their assets by trading their sparse fractional reserve dollars and trading them for speculative and volatile mortgaged backed security derivatives. These toxic assets which were given AAA ratings tanked when the housing bubble burst. Because of "mark-to-market" policies by the SEC since ENRON, derivatives are assigned their current value in todays market and not the value you think they will fetch in the future when you plan to sell them. Greenspan thought derivatives would stabilize the markets, but because of their potential for abuse we have seen wide fluctuations in gas prices, the current bank failure, and the ENRON accounting scandal as a direct result. Banks failed because when they lost their fractional reserves, they could not lend and could not pay. Consequently, some small banks were allowed to fail, other banks were bought out, and others "too big to fail" were given TARP.
Negative Effects on Family Values
As I said above, the only way for a family paying minimum payments on a home loan to accrue significant equity is for the value of the home to increase. This is the pressure that has driven the price of homes up and up. This same lending system has also pressured fathers to work more hours, multiple jobs, and for moms to also enter the labor force to meet the rising cost of living. The bubble burst and there was a correction in the market because even with both mom and dad working, the wages have not kept pace with the cost of living. But there are other more serious consequences. With the increase in "productivity" and dad working multiple jobs, and mom also in the work place at the same time (I am not against women in the work place), there is no one home to meet the critical emotional needs of the family. There is no nurturing going on. There is no one home to transmit critical life skills and preventive health to the rising generation. Consequently, when you have unmet emotional needs, that leads to addictive behavior, mental illness, delinquency, teen pregnancy and illegitimacy, gang activity, and poverty. And all of this results in rising health care needs and costs.
Preventive Medicine
Jesus Christ said, "The whole hath no need of a physician, but them that are sick." Other than vaccines which doctors don't need to do at all, Doctors do not do preventative medicine despite what we say. True primary prevention is what you learn from Mom and Dad, at school and at church. It is Mom and Dad that are supposed to teach basic principles of health, diet, nutrition, exercise, stress management, care of a newborn, first aid, etc, etc. If you have to hear this from your doctor, you are likely hearing it too late. Why, because what doctor's do is not primary prevention. What Doctors call "secondary prevention" is screening for the presence of absence of disease. If disease is present, we will institute disease management which has a cost, but in return will grant you longer life. This trade off of cost for life is called the QALY. Nothing a Doctor does saves money, it only costs money and results in longer life. But whether you die in 6 months or 6 years, the cost of dying is expensive but the same. It's a sunk cost. Even if a doctor saves you from dying of cancer, all we really did is save you to die from something else expensive. I worry about ideas of government agencies coming into the home to teach parents the state version of preventive medicine and life skills. Would such an agency have the power to remove children from a home if the parents were not teaching the mandated state doctrine of preventative care?
Dis-incentive System
The government runs the VA system and Medicare so it thinks it can run an insurance program that competes against private insurance. However the VA system and the Canadian system are propped up by the US private system. When people can't get what they need at the VA or in Canada, they go to the US private system. There is also very little incentive in the VA system to work hard and be productive. Consequently, doctors act like they are unionized and don't stay late or do that extra surgery. The consequence is more inefficiencies and longer wait times. The Fort Hood shooter was not kept on staff because of political correctness, but because they needed a doctor. He filled a spot. The US government had a lot of money invested in him. There are lots of great but many bad doctors that hide out in the VA system because they are needed and fill as call schedule. The US needs to decide if it wants to out-source doctors. Because, if you dis-incentivize the system, people will not do it. It's too tough and our brightest people will choose another career path.
Health Care Reforms
I agree with Gov/Sec Mike Leavitt that the debate is not whether we should or shouldn't cover the 50 million uninsured in America. The question is how do we do it. Do we throw up our hands and let the government handle it, or do we exercise our rights to self-government and look for other answers. There are many good ideas on the table.
1. Romney Care: subsidize the purchase of private health insurance.
2. Tort Reform: this helps both doctors and patients
3. Health Savings Accounts with Catastrophic Coverage: isn't this what health insurance should be?
4. Direct Patient/Doctor Billing: more efficient for patients to pay doctors directly and then be reimbursed by insurance.
5. Increased Interstate Competition: Let people go out of state to buy insurance.
6. Fee for Service: I disagree with Mike Leavitt that the government should only pay a set price for a diagnosis. If a person gets a pneumonia or other complication while in the hospital, the government is not paying. That sounds like the quality reform he is talking about. I am glad I work in the ER and am federally mandated to see everyone that comes in the door, because if I was a surgeon, I wouldn't dare do a surgery on 3/4 the people I see because their personal behavior, genetics, and the nature of the procedure have inherent risk of complications. And now in addition to having to treat the complication, the doctor would eat the cost of the complication. If a doctor is incompetent, they should loose their license, but complications happen. No one is out there making complications so doctors can bill more. Doctors would rather do another surgery then have to spend time dealing with a complication.
7. Pre-existing Conditions: I think this kind of policy is the kind of reform government can do. They can give insurance companies operating guidelines in which they must operate to protect the public from being taken advantage of.
8. Medicare: Why do healthy workers pay into insurance their whole life and them when they retire and it comes time for them to have the majority of healthcare costs, they get dumped and put on Medicare and become the responsibility of the US tax payer?
Facility Fee
If you want to make a big difference in health care, you need to make changes that really matter. If reducing the rising costs of health care is the goal, none of the above measures will make much of a difference. They are good suggestions. But they only represent a small percentage of the total health care costs. The real question is, where does all the money go? Well it doesn't go to the doctor. The doctor fee is only 15-20% of the total fee. After, pharmacy and insurance companies take their cut, the majority of costs go to what is called the facility fee. And those facility fee profits go to the bank, or corporate board comprised of the ultra rich who get wealthy upon the talents and labor of others based only upon the "illusion of risk." If you want health care costs to be reduced, you have to change how capital is raised, borrowed, and repaid. And this brings us back to banking and financial reform.
Financial Reform
Some people may not like this, but the model for lending/borrowing reform is the Sharia Law Islamic Banks. If you can get past the Muslim-extremist issues, the Islamic banking system is a great system. If we were to adopt this system in the US to a greater degree, it would be a great PR/political move for the West. So, what is so great about Sharia Banks? They don't collect interest, but they do make profits. I am still studying how they operate. But so, far if a person wanted to purchase a home or business, they would pay a fee to borrow the money from the bank. The bank would not lend the money directly but purchase the home or business for the individual. There would be joint ownership. The buyer could pay 10% down payment and start off as a 10% owner of the house or company. That person would then pay back the loan. With every payment, the leasee would own a greater percentage of the home or business and build immediate equity until the home is paid off.
There are interesting things that could be done to deal with profits and appreciation. There could be an arrangement that if the home or business appreciated in value during repayment, that a portion of those profits would go to the bank and the leasee according to the % ownership each had in the home or business. Individual investors in this new anti-banking institution would become part owners. When an individual opens up a savings account and deposits money, the bank would issue that individual stock. As the bank's investments and properties appreciate and earn profits, those profits would be divided among all the stock holders. A great name for the anti-bank would be the Kirtland Safety Society.
Pay Off the National Debt
The problem with being slaves to interest and indebtedness, is that the whole United States of America is a slave to the multi-national banks and foreign governments who own the bulk of our savings bonds. Right now, nearly a quarter of our yearly budget goes just to pay the interest on the national debt. That is just the interest on 10 trillion dollars. One idea that would solve our nation's debt problem and fix our banking system is to simply print 10 trillion dollars and pay off our debtors. To make sure that printing that much money doesn't devalue our currency, the US could end the practice of fractional reserve banking. The need for banks to borrow more money would offset the glut of extra dollars in the system. Then, our govenment would need to commit to balancing the budget and shun deficit spending and never again sell our savings bonds to foreign governments.
Showing posts with label Home and Family. Show all posts
Showing posts with label Home and Family. Show all posts
Monday, November 23, 2009

Friday, August 28, 2009
Financial Reform Needed for Healthcare Reform
Hospitals make profits. But where do these profits go? Not to doctors. Doctors bill separately. The facility fee is the major cost of care. If the hospital is paid for the profits go to share holders. If the hospital has a mortage, because of the amortization schedule all the profits go to pay interest on the hospital mortgage, which goes to the banks which goes to other shareholders.
Look at what banks can do. They barrow money for almost free from the US gov with no amortization. They lend 10x that amount due to fractional reserve lending, and they collect 90% interest due to amortization for 20 years on a 30-year loan. When you save money you don't get significant interest until 20 years off. This creates a natural division or class system. Only a few people can break through the wealth barrier.
Business profits, stock dividends, US gov debt interest and hospital profits all go to the same ultra-rich, ultra-elite. Smaller banks would have never failed had they not been dupped into trading their 1/10th fractional cash reserves for worthless mortgage-backed securities.
We need to change how we lend and borrow money. The current system enslaves families and workers. I am all for profits and a free market, but the current system is a monopoly favoring the envestment bankers and ultra-elite. Locking us into our current banking and lending system is the motivation behind plans for a world bank and the cap-and-trade legislation. Furthermore, our current lending systems is responsible for the current housing problems, rising healthcare costs, stress on families, and the failure of the 3rd-world to industrialize.
If you don't believe what easy capital and credit can do, just look at what micro-credit is doing in 3rd-world countries and what school loan programs in the US can do to make higher education affordable and accessible for all.
Look at what banks can do. They barrow money for almost free from the US gov with no amortization. They lend 10x that amount due to fractional reserve lending, and they collect 90% interest due to amortization for 20 years on a 30-year loan. When you save money you don't get significant interest until 20 years off. This creates a natural division or class system. Only a few people can break through the wealth barrier.
Business profits, stock dividends, US gov debt interest and hospital profits all go to the same ultra-rich, ultra-elite. Smaller banks would have never failed had they not been dupped into trading their 1/10th fractional cash reserves for worthless mortgage-backed securities.
We need to change how we lend and borrow money. The current system enslaves families and workers. I am all for profits and a free market, but the current system is a monopoly favoring the envestment bankers and ultra-elite. Locking us into our current banking and lending system is the motivation behind plans for a world bank and the cap-and-trade legislation. Furthermore, our current lending systems is responsible for the current housing problems, rising healthcare costs, stress on families, and the failure of the 3rd-world to industrialize.
If you don't believe what easy capital and credit can do, just look at what micro-credit is doing in 3rd-world countries and what school loan programs in the US can do to make higher education affordable and accessible for all.
Tuesday, August 25, 2009
Secondary Preventive Care Does Not Reduce Health Care Costs
The saying goes, "an ounce of prevention is worth a pound of cure." And that is true when you are talking about primary prevention. Primary prevention is what your mom and dad taught you growing up, such as hygiene, proper diet, exercise, how to handle stress, and spiritual faith so as to not harbor an irrational fear of death. This health knowledge and these life skills can and should be reinforced at school and at church. But they are primarily taught at home to children so that they become habitual and part of a culture of health. Hopefully, these life skills are passed on from one generation to another from parents and grandparents to children and between siblings and neighbors. In case where there are gaps in proper health knowledge and behavior, a pediatrician or other doctor and help remind and reinforce these lessons with parents so that this culture can be perpetuated in the rising generation. However, in a healthy culture, it is the parents that are the primary providers of health skills and disease prevention and not the doctors.
Other than vaccines, which can be given by non-doctors, medicine is not in the business of primary prevention. Doctors really don't have the time needed to transmit information on diet, meal preparation, hygiene, exercise, emotional wellness, end-of-life issues, and substance abuse avoidance. And even when doctors discuss these issues with patients the discussion rarely results in a change of behavior. Furthermore, by the time the topic comes up, the patient probably already has whatever disease the health information would have prevented. And because habits are hard to break, very few people are able to make the changes in their behavior that may slow or even reverse the disease.
There is a myth floating around that more doctor-based prevention will lower health costs. While primary prevention does lower health costs, the truth is, that other than vaccines, doctors do very little primary prevention. Secondary prevention is what physicians do. What is secondary prevention? Secondary prevention involves early detection of disease--period. So, in actual fact, there really is no prevention in secondary prevention. Secondary prevention does nothing to prevent disease onset, it only detects that disease process once it has begun.
Some might think that a doctor's focus only on disease is wrong and doctors should do more disease prevention. However, the reality is, medical doctors are trained and equipped to treat disease. Treating and managing disease is what doctors do. Like Jesus Christ said, "they that are whole have no need of the physician, but they that are sick."
Think about what happens when an adult visits their doctor. Your doctor will likely conduct a series of medical screening tests such as a lipid profile, a fasting glucose challenge, prostate specific antigen, and a colonoscopy. The purpose of these tests are for one purpose only, and that is to detect the presence of disease. None of these tests prevent chronic diseases such as diabetes, hypertension, coronary artery disease, chronic lung disease, dementia, or depression from developing. Only an interplay of genetics, environment, and behavior lead to disease or lead to health. That said, newer genetic testing, and testing for vitamin D deficiency or high cholesterol can inform patients of their risk factors for developing certain diseases, still, the prevention of disease still rests with behavior. That is why real prevention needs to begin at home with parents and children.
But doesn't the early detection of disease like cancer save money? You think it would, but in reality, early detection of disease actually increases health care costs. You don't believe me? We all have been told that 2/3 of health care expenses occurs within the last 6 months of life. With this in mind, it really doesn't matter if you die 6 months from now or 6 years from now, those costs will be the same. What secondary prevention and early disease detection do is make it possible for doctors to slow the progress of disease and therefore extend lifespan. But eventually, one disease or another will progress, become expensive, and kill you. Yes, early detection and management of disease will result in longer life, but that longer lifespan comes at a cost. So, in reality the kind of prevention that doctors do increases health care costs instead of lowering them. This is especially true if you are retired and no longer contributing value to society. And even in the case where a disease can be cured or reversed, the curing of that one disease will only lead to you dying of some other incurable disease.
The cost of disease management and treatment has a name and is assigned a value. Doctors and epidemiologists refer to the cost of disease treatment in exchange for life as the QALY or Quality Adjusted Life Year. A QALY tells doctors, insurance companies, health policy bureaucrats, and patients the cost of a particular disease treatment vs. benefit in terms of quality and quantity of life gained. Every disease treatment and procedure in medicine has a QALY associated with it. The QALY is the cost to manage disease. To give you an idea of what the QALY is and its value, kidney dialysis is the gold standard. Historically, kidney dialysis for those who have suffered complete kidney failure has a QALY of $50,000 per quality-adjusted life year. That means for every good year a dialysis patient gets from being on dialysis, the treatment costs the medical system $50,000. Treatments and procedures less than this mark are considered a good deal, while interventions more expensive than this $50,000 mark are of questionable value.
You can view QALY values by entering the following term into Google: QALY League Tables
If you detect a disease early you may begin by instituting low cost/benefit interventions, but eventually as the disease progresses, the high cost/benefit interventions will follow. Therefore, the only real result of early disease detection is that the low cost/benefit interventions will get implemented before the high cost/benefit interventions. Again, while implementing low cost/benefit interventions will prolong life, it only adds to the bottom line.
Now, please to not misunderstand my intent in writing this post. I am not suggesting that medicine or government or anyone should advocate that disease should not be detected and treated early. My point is that when we talk about reducing medical care costs, we need to be clear about how our health care system is organized, how it operates, and what are its associated costs. Only by a clear understanding of the system can we hope to implement changes to maximize its efficacy and efficiency.
Other than vaccines, which can be given by non-doctors, medicine is not in the business of primary prevention. Doctors really don't have the time needed to transmit information on diet, meal preparation, hygiene, exercise, emotional wellness, end-of-life issues, and substance abuse avoidance. And even when doctors discuss these issues with patients the discussion rarely results in a change of behavior. Furthermore, by the time the topic comes up, the patient probably already has whatever disease the health information would have prevented. And because habits are hard to break, very few people are able to make the changes in their behavior that may slow or even reverse the disease.
There is a myth floating around that more doctor-based prevention will lower health costs. While primary prevention does lower health costs, the truth is, that other than vaccines, doctors do very little primary prevention. Secondary prevention is what physicians do. What is secondary prevention? Secondary prevention involves early detection of disease--period. So, in actual fact, there really is no prevention in secondary prevention. Secondary prevention does nothing to prevent disease onset, it only detects that disease process once it has begun.
Some might think that a doctor's focus only on disease is wrong and doctors should do more disease prevention. However, the reality is, medical doctors are trained and equipped to treat disease. Treating and managing disease is what doctors do. Like Jesus Christ said, "they that are whole have no need of the physician, but they that are sick."
Think about what happens when an adult visits their doctor. Your doctor will likely conduct a series of medical screening tests such as a lipid profile, a fasting glucose challenge, prostate specific antigen, and a colonoscopy. The purpose of these tests are for one purpose only, and that is to detect the presence of disease. None of these tests prevent chronic diseases such as diabetes, hypertension, coronary artery disease, chronic lung disease, dementia, or depression from developing. Only an interplay of genetics, environment, and behavior lead to disease or lead to health. That said, newer genetic testing, and testing for vitamin D deficiency or high cholesterol can inform patients of their risk factors for developing certain diseases, still, the prevention of disease still rests with behavior. That is why real prevention needs to begin at home with parents and children.
But doesn't the early detection of disease like cancer save money? You think it would, but in reality, early detection of disease actually increases health care costs. You don't believe me? We all have been told that 2/3 of health care expenses occurs within the last 6 months of life. With this in mind, it really doesn't matter if you die 6 months from now or 6 years from now, those costs will be the same. What secondary prevention and early disease detection do is make it possible for doctors to slow the progress of disease and therefore extend lifespan. But eventually, one disease or another will progress, become expensive, and kill you. Yes, early detection and management of disease will result in longer life, but that longer lifespan comes at a cost. So, in reality the kind of prevention that doctors do increases health care costs instead of lowering them. This is especially true if you are retired and no longer contributing value to society. And even in the case where a disease can be cured or reversed, the curing of that one disease will only lead to you dying of some other incurable disease.
The cost of disease management and treatment has a name and is assigned a value. Doctors and epidemiologists refer to the cost of disease treatment in exchange for life as the QALY or Quality Adjusted Life Year. A QALY tells doctors, insurance companies, health policy bureaucrats, and patients the cost of a particular disease treatment vs. benefit in terms of quality and quantity of life gained. Every disease treatment and procedure in medicine has a QALY associated with it. The QALY is the cost to manage disease. To give you an idea of what the QALY is and its value, kidney dialysis is the gold standard. Historically, kidney dialysis for those who have suffered complete kidney failure has a QALY of $50,000 per quality-adjusted life year. That means for every good year a dialysis patient gets from being on dialysis, the treatment costs the medical system $50,000. Treatments and procedures less than this mark are considered a good deal, while interventions more expensive than this $50,000 mark are of questionable value.
You can view QALY values by entering the following term into Google: QALY League Tables
If you detect a disease early you may begin by instituting low cost/benefit interventions, but eventually as the disease progresses, the high cost/benefit interventions will follow. Therefore, the only real result of early disease detection is that the low cost/benefit interventions will get implemented before the high cost/benefit interventions. Again, while implementing low cost/benefit interventions will prolong life, it only adds to the bottom line.
Now, please to not misunderstand my intent in writing this post. I am not suggesting that medicine or government or anyone should advocate that disease should not be detected and treated early. My point is that when we talk about reducing medical care costs, we need to be clear about how our health care system is organized, how it operates, and what are its associated costs. Only by a clear understanding of the system can we hope to implement changes to maximize its efficacy and efficiency.
Sunday, May 31, 2009
Freedom of Opportunity
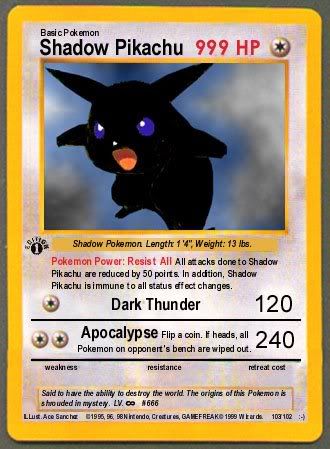 My son Devin (8) and I were playing Pokemon today. The past few weeks I have been showing him how to divide up the cards by color, and select the best proportion of 60 Pokemon, energy, and supporter cards he should use to win. So far, I have won the first 2 games. The first game we randomly divided the supporter cards and I played a purple-green deck, and this time I let Devin play the purple-green deck and I played the blue-pearl deck. Despite the 2 defeats, Devin has taken the loses well.
However, despite my helping Devin play the game better, my wife Ruth wondered if it wouldn't be better for Devin's self-esteem if I let him win every once in a while. Let him win?!! I don't know why these types of comments continue to surprise me. We will have been happily married for 10 years this June. And I knew when I married her that she was a bit of a "social progressive." But, if sometimes a little thing like a card game can suddenly become a metaphor for life and politics and everything that is wrong with America, this is a time.
Even though I disagree on this issue, I do appreciate and value my wife's empathetic perspective. However, I think we have been doing a little too much letting people win in America instead of helping people compete. I mean, who are we kidding if we just lower our expectations for people. And what kind of satisfaction and self-esteem does a person really derive from a victory if they know the game was rigged from the start.
Ruth did say, that her reasoning for wanting me to let Devin win was that she didn't want Devin to take out his frustration on his younger cousin Cameron by endlessly thrashing him every time they play Pokemon together. That is a bit of a red herring. No one wants that. In stead, I am hoping he will do as I have done with him and help his cousin to become a better Pokemon player as well.
This is the difference between equality of opportunity verses equality of results and the Founding Fathers established this nation based on the prior principal over the later. Unfortunately, through LBJ's "great society" and similar socialist legislation since, our country has been focused on lowering expectations and letting people think they are winning at the game of life instead of empowering people to truly succeed.
Tuesday, July 25, 2006
Saturday, June 10, 2006


Saturday, April 08, 2006

Thursday, October 20, 2005

Friday, April 08, 2005


Subscribe to:
Posts (Atom)


